 By Salary by Career
New Treasury rules will automatically create investment accounts for millions of children, but parents may still need to act before some money can actually reach those accounts.
Automatic Enrollment Changes the Starting Point
View this post on Instagram
Parents no longer have to be the first person to put the machinery in motion.
Treasury’s temporary regulations released Sept. 29 allow automatic enrollment in Trump Accounts for eligible children instead of requiring a parent or another authorized person to initiate account creation. More than 60 million children under 18 could be added under the expanded system.
Previously, account creation largely depended on a parent or another authorized person making an election. Under the new structure, Treasury can establish what the regulations call an “auto account” on a child’s behalf.
That changes a basic practical problem. A family can miss a form, ignore an email, or simply put a financial task aside for six months.
Automatic enrollment removes that first bottleneck. Account creation, though, is only one part of the process. Some money is less self-starting.
An Account Is Not the Same as the $1,000
Confusion is easy here because automatic enrollment sounds broader than it is.
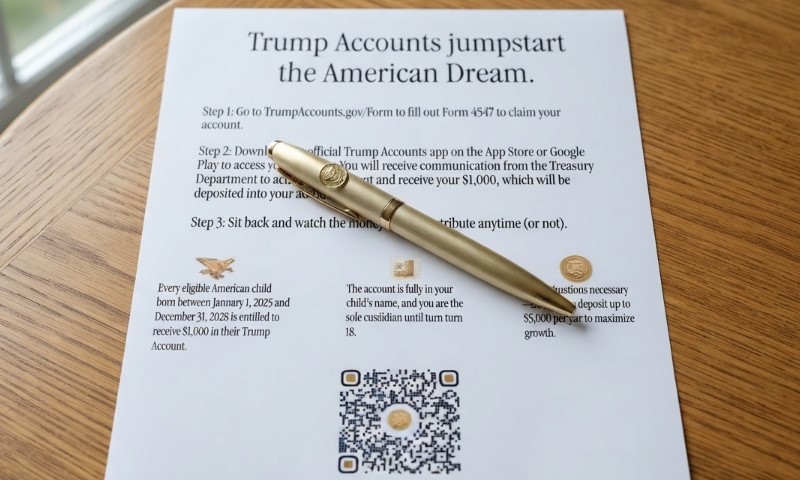
Children born in 2025, 2026, 2027, or 2028 can qualify for a one-time $1,000 federal pilot contribution if they meet program requirements. Automatic creation of Trump Accounts does not, by itself, make that $1,000 payment happen. An eligible person still has to make the pilot-program election.
Treasury cannot make that pilot election on a family’s behalf. Once the required election has been made, an auto account can accept the $1,000 contribution even before a parent or guardian claims full control of the account.
That distinction matters more than the terminology. A child can have an account sitting there, legally established and ready to hold certain assets, without automatically receiving every dollar associated with the program.
What an Auto Account Can Actually Receive
Auto accounts are deliberately limited before an authorized adult claims them.
During a child’s growth period, an unclaimed auto account can accept qualified general contributions and the $1,000 pilot payment after the required pilot election.
Family contributions and employer contributions generally cannot go into that auto account while it is still unclaimed.
Once a parent, guardian, or other person with legal authority claims the account, assets can be transferred into a claimed initial Trump Account. At that point, the account can accept contribution types permitted under the broader Trump Account rules.
Put more simply, opening the door can now happen automatically. Using everything available behind it still takes human action.
Why Treasury Changed Course
Earlier rulemaking raised a difficult privacy problem.
Broad automatic enrollment created questions about protected tax and financial information. Treasury and the IRS needed a structure that could create and invest millions of Trump Accounts without unnecessarily exposing identifying information connected to each child.
Officials landed on a master group trust.
Assets tied to auto accounts can be invested collectively through that trust while records still identify each child’s share. Account-level tax information stays in a safeguarded environment, while the trustee can handle trust transactions without receiving identifying return data for every beneficiary involved.
So what changed? Privacy concerns did not simply disappear. Treasury changed the mechanics around them.
Scale Changes What Donors Can Reach
Automatic enrollment also changes the size of the pool available for outside contributions.
More than 60 million additional children could have Trump Accounts created under the new approach.
One major private commitment already attached to the program is Michael Dell’s $6.25 billion pledge, and broader enrollment could allow major charitable commitments to reach many more children.
That is an important consequence of default enrollment. Donors do not have to rely entirely on millions of families completing account-opening steps before an eligible group can receive qualified contributions.
Contribution Rules Still Have Fine Print
Qualified general contributions can be funded by eligible government entities, tribal governments, and tax-exempt organizations, then distributed in equal amounts to account holders in a qualifying class.
Those contributions do not count against the ordinary $5,000 annual contribution limit.
Other contributions face different rules. Employer contributions and money added by family members generally count toward the $5,000 annual limit during the growth period, with inflation adjustments scheduled after 2027.
For families, that means Trump Accounts may exist automatically while contribution choices still depend on who is adding the money, what type of contribution it is, and if the account has been claimed.
Less Paperwork Doesn’t Mean No Paperwork
Automatic enrollment solves one administrative problem: getting Trump Accounts established for eligible children.
Parents still have decisions to make after that point. Families seeking the $1,000 pilot contribution need the required election, and anyone wanting to add ordinary family or employer money generally needs an account that has been claimed.
A better question for many parents may no longer be, “Do I need to open one?” It may be, “What do I need to do with the one my child already has?”